G-SFIA2026 | Global Space Financial Innovation Alliance Conference


JOIN
PEATIX

G-SFIA Global Space Financial Innovation Alliance / Capital has no gravity / 11.4 Wed 2026 @Global Business Hub Tokyo

TICKET

Get your ticket

Registration is handled through Peatix.
Early Bird tickets are available.

Register on Peatix→

Registration closes as soon as the venue is full.

ABOUT

The space business enters the age of
industry, academia, government — and finance.

G-SFIA is a conference that creates the crossing point between the commercialization of the space industry and finance and investment.

A keynote, panel discussions on satellite use and public-private collaboration, a startup pitch, and networking at the Rooftop Night — all in a single day.

PROGRAM

How the day runs

Part 1 | Main Conference
13:00-17:30 / Global Business Hub Tokyo

13:00 – 13:10

Welcome / Opening

Makoto Shibata (FINOLAB) / Yoshimasa Hayashi (Minister for Internal Affairs and Communications)


Makoto Shibata of FINOLAB opens the day, followed by an opening speech from Yoshimasa Hayashi, Minister for Internal Affairs and Communications.

13:10 – 13:20

“Shichifukujin”

Nagauta dance

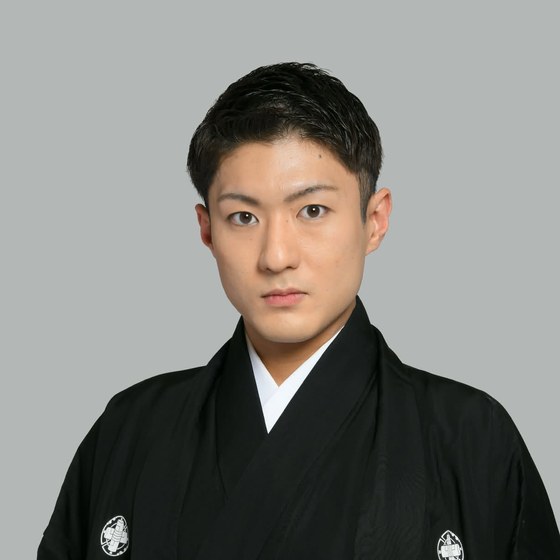
Dancers Hashinosuke Nakamura / Naozo Fujima
Nagauta Mimiro Kineya / Eijiro Kineya


About the piece

“Shichifukujin” is widely known as a celebratory Nagauta dance. The first half sings of the founding of Japan; in the second half Ebisu, one of the Seven Lucky Gods, appears and a string of auspicious wordplay on the verb “hiku” (to draw, to pull) unfolds.

Despite the title, Ebisu is the only one of the seven who appears. He is the god of prosperity in business and of good fortune — blessings close to everyday life.

13:20 – 14:00

Panel Discussion 1

The future of space entertainment

Moderator Hidetaka Aoki (Space Port Japan)
Hashinosuke Nakamura (Kabuki actor) / Masayoshi Boku (Bascule) / Naoko Yamazaki (Astronaut)

14:00 – 14:40

Panel Discussion 2

When space becomes ordinary

Moderator Mitsunobu Okubo (Digital Agency / Ministry of Finance)
Kazuo Takubo (JAXA) / Tsubasa Nara (Mizuho Bank) and others

14:40 – 15:00

Keynote

Hermann Ludwig Moeller (Director, European Space Policy Institute)


Director of the European Space Policy Institute (ESPI), Europe’s think tank on space. From a position of promoting European space policy globally and providing independent analysis and recommendations to decision makers and institutions, he speaks on where space and capital stand today.

15:00 – 15:40

Startup Pitch

Startups building businesses across space and finance take the stage

GLODAL / GlobalX / Nudge / Ridge-i / Zero Industries / Saga Space Ventures


Space and fintech startups each share what they are building right now.

15:45 – 16:25

Panel Discussion 3

Space risk and how to hedge it

Moderator Mihoko Shintani (TMI Associates)
Hiro Hayashi (Mitsui Sumitomo Insurance) / Kentaro Iwanaga (Ministry of Economy, Trade and Industry)

16:25 – 16:55

Panel Discussion 4

Proving place and time

Moderator Taichi Furuhashi (Aoyama Gakuin University)
Takahiro Shinohara (Data Trust) / Kakuta Inoue (Dentsu Soken)

16:55 – 17:30

Panel Discussion 5

Measuring creditworthiness from orbit

Moderator Naohiko Kohtake (Keio University Graduate School of SDM)
Makoto Goda (Nihon Shokubutsu Nenryo) / Naruo Kanemoto (Space Shift)

Part 2 | Rooftop Night
18:00-20:00 / SKYLAB, Otemachi Building rooftop

18:00 – 20:00

Rooftop Night

Networking between speakers and attendees


We take over SKYLAB, the rooftop of the Otemachi Building, for networking between speakers and attendees. Under the night sky in the middle of Tokyo, the interest sparked during the day turns straight into a next step.

18:00-20:00 / SKYLAB, Otemachi Building rooftop (about 5 min walk from the main venue)

SPEAKERS

Speakers
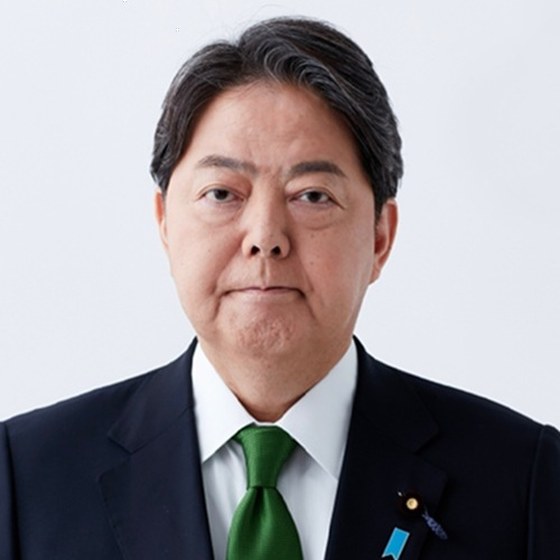

Yoshimasa Hayashi

Yoshimasa Hayashi

Former Minister for Internal Affairs and Communications
Member of the House of Representatives

PROFILE
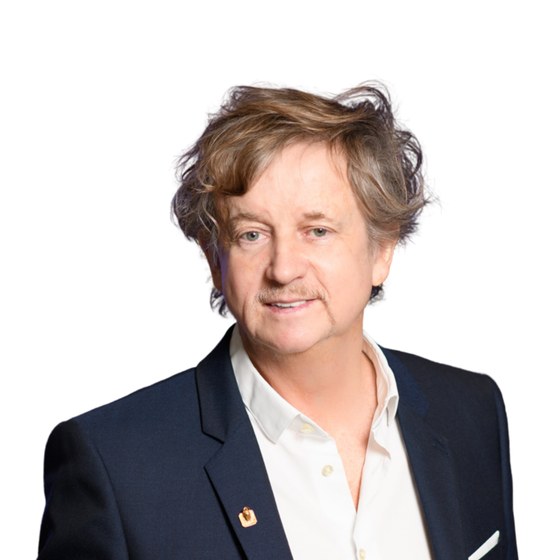
He entered politics after working at Mitsui & Co., Sanden Kotsu and Yamaguchi Gogo Gas, and has served five terms in the House of Councillors and three in the House of Representatives. He has previously held office as Minister for Internal Affairs and Communications, Chief Cabinet Secretary, Minister for Foreign Affairs, Minister of Education, Culture, Sports, Science and Technology, Minister of Agriculture, Forestry and Fisheries, Minister of State for Economic and Fiscal Policy, and Minister of Defense. He is a graduate of the Faculty of Law, the University of Tokyo, and holds an MPA from the Harvard Kennedy School.

Hermann Ludwig Moeller

Hermann Ludwig Moeller

European Space Policy Institute (ESPI)
Director

PROFILE
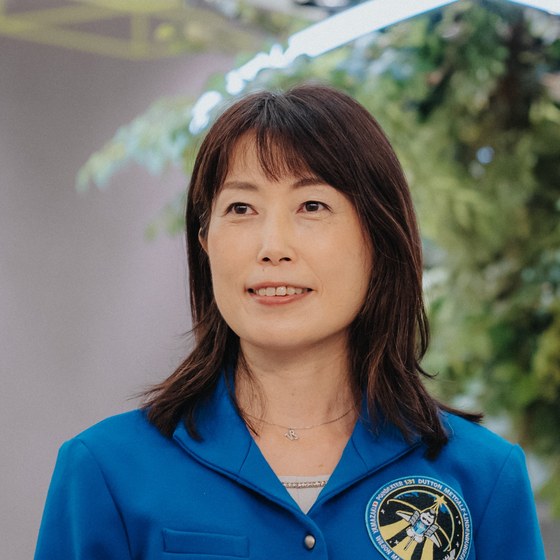
Since 2022, Hermann Ludwig Moeller is the Director of the European Space Policy Institute (ESPI) in Vienna, the European Think Tank on Space, elected for a second term 2025-2028. ESPI is promoting European Space Policy globally, is providing independent analysis, proposals and recommendations to European decision makers and institutions and is raising public awareness on strategic space issues. Prior to joining ESPI, he held leading positions at ESA in the creation of the EU Copernicus Earth Observation programme and in the preparation of the EU Secure Connectivity initiative as Head of Copernicus Space Segment Office and Head of Telecommunications Strategy, Programme and Transformation Office. Mr. Moeller has more than 20 years of experience in operating with high level leadership in a complex multi-stakeholder environment with national space agencies, ESA member states, at EU level and with EUMETSAT, as well as in public-private partnerships with industry. He was awarded the ESA Douglas Marsh Fellow at NASA and contributed to the creation of the European Internet backbone. He gained first professional experience at the European Patent Office HQ and Siemens HQ. Mr. Moeller holds a master degree in telecommunications, following studies at Technical University Darmstadt and Ecole Nationale Supérieure de Télécommunications (ENST) – Télécom Paris. He is of German nationality with working experience in Germany, Italy, the USA, The Netherlands, France and Austria, is married and father of four children.

Naoko Yamazaki

Naoko Yamazaki

Astronaut
 

PROFILE
Yamazaki was selected as an astronaut candidate by the Japan Aerospace Exploration Agency (JAXA) in 1999 and flew aboard Space Shuttle Discovery on the STS-131 mission to the International Space Station in 2010. Following her retirement from JAXA in 2011, she served on Japan’s National Space Policy Committee (2012-2022). She co-founded Space Port Japan Association in 2018 and serves as its Representative Director. She is also a Council Member of The Earthshot Prize to protect our home planet, President of Young Astronaut Club Japan, and, since 2025, General Manager of Vast Japan. She holds a Ph.D. in Engineering from the University of Tokyo.

Hashinosuke Nakamura

Hashinosuke Nakamura

Kabuki Actor
 

PROFILE
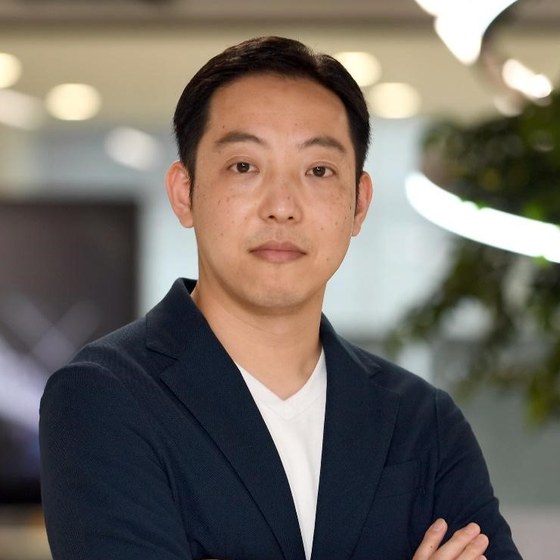
Born 26 December 1995, the eldest son of Nakamura Shikan. He made his stage debut in September 2000 at the Kabukiza, taking the name Nakamura Kunio I in Kyoganoko Musume Dojoji and Kikubare Ikioi Wakakoma. In October and November 2016 he succeeded to the name Nakamura Hashinosuke IV, appearing as Tsutsumi Gunji and other roles in Ichinotani Futaba Gunki: Kumagai Jinya at the Kabukiza. In recent years he has taken leading classical roles such as Nuregami Chogoro in Futatsu Chocho Kuruwa Nikki: Hikimado and Aoyama Harima in Bancho Sarayashiki at the New Year Asakusa Kabuki and the Minamiza March Kabuki. He has also widened his range into new kabuki, including Shinsaku Kabuki Final Fantasy X. At the fourth Kamiyacho Ko-Kabuki in 2026 he played the long-awaited title role in Sakanaya Sogoro, as well as the uncle Yasugi Matsunojo in Akutaro.

Hidetaka Aoki

Hidetaka Aoki

Space Port Japan, Co-Founder & CEO
Space Evangelist®

PROFILE
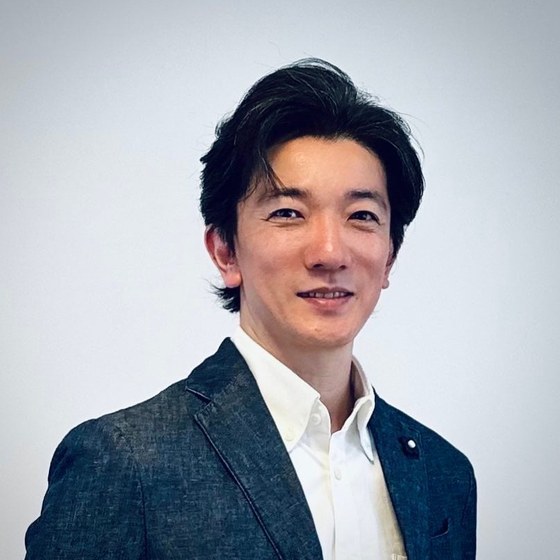
As a “Space Evangelist”, Hide Aoki promotes Japan’s private-sector-led space industry through his expertise in business and technology. After earning a master’s degree in aerospace engineering and a pilot’s licence in the U.S., he joined Mitsubishi Electric, where he worked on Japan’s first cargo spacecraft, Kounotori, and the SLIM lunar lander. He has supported space start-ups as an investor for over 10 years. He also co-founded SPACETIDE Foundation and serves as CEO of Space Port Japan. In addition, he contributes to JAXA and government committees through his broad experience in the space sector.

Mitsunobu Okubo

Mitsunobu Okubo

Digital Agency / Ministry of Finance
Deputy Chief Information Officer

PROFILE
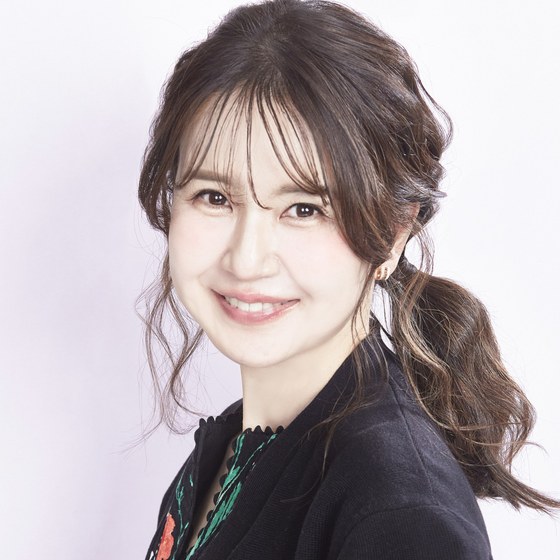
Japan’s representative to the ASEAN+3 expert dispatch programme for civil service cooperation, and an advisor to the Financial Data Utilization Association. A cross-sector player who also serves as a municipal CIO and a visiting MBA professor. After founding a company in the U.S. as a student, he worked as an architect for internet banking at Dentsu Soken. He has previously served as CTO of Mizuho FG / BlueLab, as a mentor for the Tokyo Metropolitan Government’s foreign company attraction programme, and as an advisor to the Financial Services Agency. Through pro bono work he mentors startups and builds ties with industry bodies abroad, helping shape the ecosystem for financial innovation.

Mihoko Shintani

Mihoko Shintani

TMI Associates
Partner

PROFILE
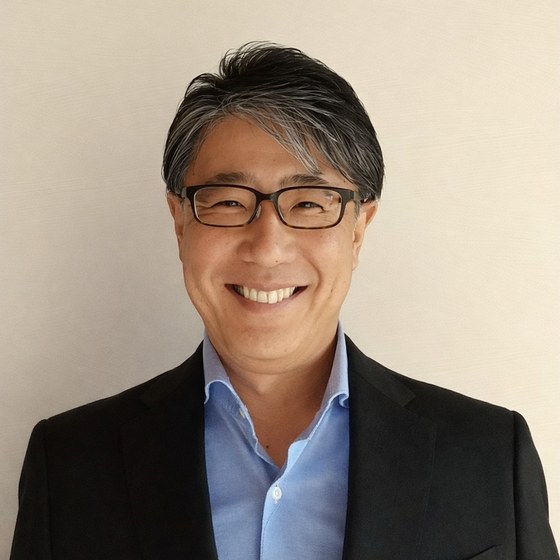
Ms. Shintani has been practicing law in Japan for over 20 years, building a distinguished career in aerospace, defense, and technology law. After pursuing graduate studies at Columbia Law School, she has spent over 13 years devoted to the space industry, advising both legacy aerospace corporations and emerging startups on complex business transactions, venture investments, and risk management. She has extensive experience managing major disputes and high-profile cases, including large-scale projects for Japan’s Ministry of Defense. Beyond her practice, she has actively contributed to national policy, serving on Japan’s Space Policy Committee, including the Security Subcommittee and the Transport Subcommittee, and participating in recent legislative reforms in the aerospace sector. She also serves as an outside director at Rapidus Inc., a national strategic semiconductor company. Her work extends to Deep Tech industries, including aerospace, defense, and frontier technologies, where she provides legal guidance on complex business transactions and strategic initiatives.

Hiro Hayashi

Hiro Hayashi

Mitsui Sumitomo Insurance Co., Ltd.
Senior Specialist, Aerospace

PROFILE
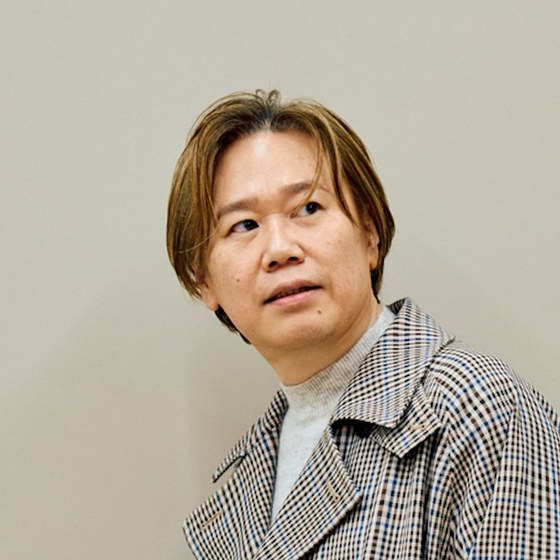
With over 35 years of experience in the insurance industry, including 12 years in space and aviation insurance. He is currently the only Senior Specialist in the Aerospace field at Mitsui Sumitomo Insurance, where he leads initiatives in risk management for space businesses and actively promotes space insurance as a method of risk hedging. Since joining the company he has been responsible for client relations with the Ministry of Land, Infrastructure, Transport and Tourism, major railway operators, and leading electronics and automobile manufacturers. He lectures on aviation law at Keio University’s Faculty of Law and at the Faculty of Law of Gakushuin University, and appears frequently in media interviews and publications. Having been stationed in London and Sydney, he brings a wealth of international experience and expertise in arrangements such as Global Insurance Programs. He is a Board Member of the Japan Space Forum.

Masayoshi Boku

Masayoshi Boku

Bascule Inc.
CEO / Creative Director

PROFILE
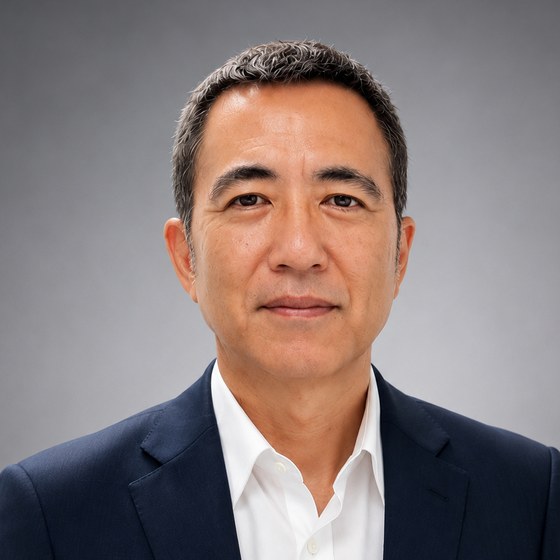
He founded Bascule in 2000. Using technology, he creates experiences that cut across advertising, broadcasting, sport, cities and space, and has won several hundred international creative awards. In 2020, in a co-creation with JAXA, he launched “KIBO Space Broadcasting Station”, connecting the International Space Station with the ground. At Expo 2025 Osaka, Kansai he worked on the experience design of two signature pavilions and delivered the Expo’s first interactive live event linking the ISS with the venue. In 2026 he launched “TerraCaster”, an Earth-observation video platform, in earnest together with Nippon Television. He works to bring the view of Earth from space into everyday life and to create space entertainment anyone can take part in.

Takahiro Shinohara

Takahiro Shinohara

Data Trust Ltd.
President & CEO

PROFILE
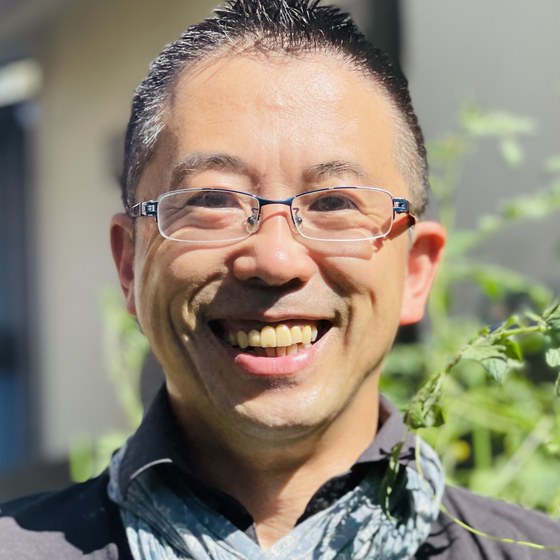
Since 1998 he has been engaged in mobile network planning, coverage design and quality optimization. From 2001 to 2015 he worked within the Kyocera Group, contributing to telecommunications technologies and businesses during a period of rapid growth in the mobile communications industry. In 2015, recognizing the significant potential of integrating mobile communications with Global Navigation Satellite System (GNSS) technologies, he founded Enabler Ltd. In 2018 he co-founded ALES Inc. with SoftBank Corp. and led the commercialization of high-precision positioning information services. Since 2021 he has been working on the design and development of an “Information Trust Infrastructure” that integrates communications, positioning, cryptographic and blockchain technologies. In 2025 he founded Data Trust Ltd. Today he is focused on establishing the authenticity of location, time and digital data, with the goal of building a “Verifiable Information Trust Infrastructure” for AI agents, finance and industry.

Taichi Furuhashi

Taichi Furuhashi

Professor, Aoyama Gakuin University
President & CEO, MAPconcierge Inc.

PROFILE
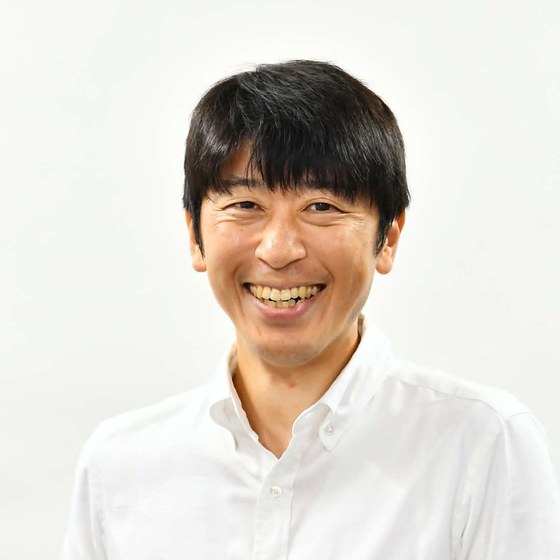
Chair of Crisis Mappers Japan, a collaborating researcher at the Center for Spatial Information Science at the University of Tokyo, and a member of OpenStreetMap Foundation Japan and the Japan chapter of the OSGeo Foundation. He holds a master’s degree in environmental studies from the Graduate School of Frontier Sciences, the University of Tokyo. His fields are cartography and spatial information science. Centred on the use of geospatial information, he provides technical consulting and teaching on Google geo services, open-source GIS and open data (OpenStreetMap, PLATEAU, the Tokyo Digital Twin and others). In recent years, under the banner of turning every citizen into a surveyor, he has thrown himself into OpenStreetMap, criss-crossing the field with panoramic imaging and drones to make maps.

Kakuta Inoue

Kakuta Inoue

Dentsu Soken Inc., Business Development Office
Chief Producer, BizDev Team

PROFILE
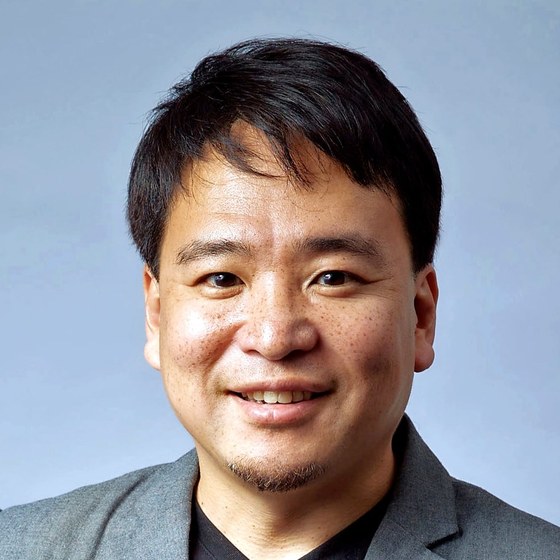
From 1999 he worked as a systems engineer at an IT company within a trading house group, handling financial systems development, new business development in the M2M field and support for overseas startups entering Japan. In 2016 he joined Information Services International-Dentsu (now Dentsu Soken), where he ran a community space for fintech startups and worked on the company’s own new business development. He joined FINOLAB, Inc. at its founding, focusing on business development support for corporates and on startup support, helping create and grow new businesses. In 2026 he returned to the Business Development Office at Dentsu Soken, where he now works on exploring new business opportunities and building new businesses.

Naruo Kanemoto

Naruo Kanemoto

Space Shift, Inc.
CEO & Founder

PROFILE
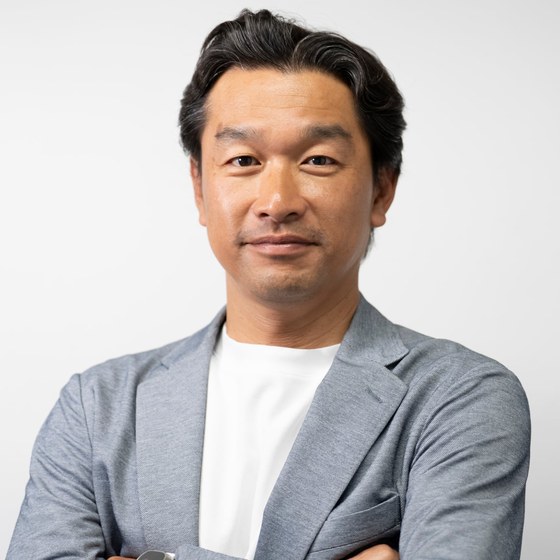
Naruo Kanemoto is a Japanese entrepreneur and the CEO / Founder of Space Shift, Inc., one of Japan’s first multinational space startups. With a background in machine learning, Kanemoto’s career journey spans from the music industry to the space sector, giving him a broad range of skills and experiences. In 2009 he established Space Shift, which focuses on developing software for satellite data analysis using AI and machine learning. Beyond his leadership at Space Shift, Kanemoto is also involved in consulting for non-space companies, helping them integrate space technologies into their businesses. He is a member of the Japanese Ministry of Internal Affairs and Communications’ Conference on Space x ICT and the Future Vision of Space Utilisation, contributing to the direction of space-related policies and innovations in Japan.

Naohiko Kohtake

Naohiko Kohtake

Keio University
Professor, Graduate School of System Design and Management

PROFILE
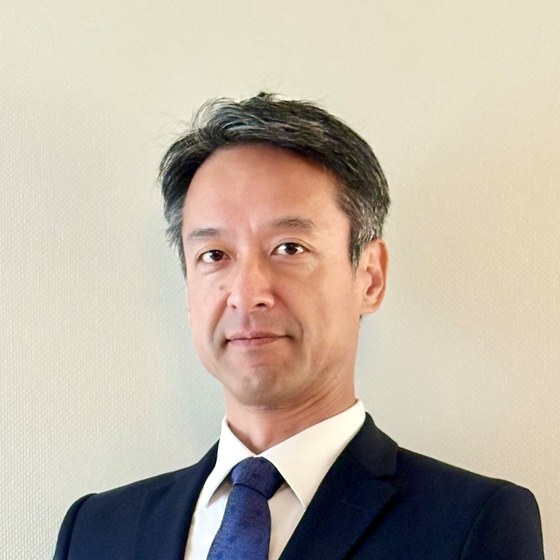
After completing his graduate studies at the Graduate School of Science and Technology, Keio University, he joined the National Space Development Agency of Japan, where he worked on the development and launch of the H-IIA rocket. Following a research post at the European Space Agency (ESA), he served as a principal engineer at JAXA, leading independent verification and validation of software for the International Space Station and satellites, and handling international cooperation with NASA and ESA on spacecraft software. He moved to Keio University in 2009. He has since served as a visiting professor at the Asian Institute of Technology, an advisor to the High Performance Strategy Division of the Japan Sport Council, and Principal of Keio Yokohama Elementary School. He is a director of the Japan Institute of Navigation, a steering committee member of Multi-GNSS Asia, and Representative Director of the Space Service Innovation Lab. He is also a visiting professor at the Center for Design Research, Stanford University, and a visiting professor at the Institutes of Innovation for Future Society, Nagoya University. PMI PMP. Ph.D. in Media and Governance.

Kazuo Takubo

Kazuo Takubo

Japan Aerospace Exploration Agency (JAXA)
Senior Advisor, Business Development and Industrial Relations Dept. / Space Strategy Fund Dept.

PROFILE
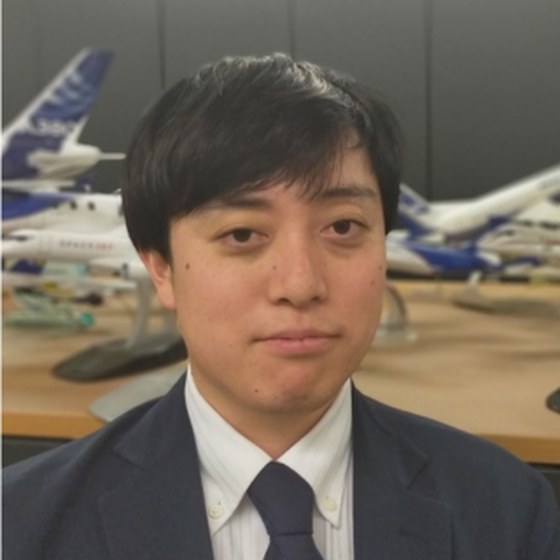
He spent some 30 years in banking, working in structured finance and overseas operations. A posting in Europe showed him how highly Japanese engineering and quality are regarded abroad, and he moved into the space sector wanting to build on that strength as a new industry for the world. At JAXA he now supports companies entering and commercializing in the space field, and works to expand the flow of capital into the space industry and to build momentum for industrial support from financial institutions.

Kentaro Iwanaga

Kentaro Iwanaga

Space Industry Division, Manufacturing Industries Bureau, METI
Deputy Director

PROFILE
Kentaro Iwanaga joined the Ministry of Economy, Trade and Industry (METI), Japan, in 2017. He has worked on policies related to trade control, economic security, information technology, and the aircraft industry, including the development of aircraft industry strategies, technology development programs, and supply chain resilience initiatives. Since July 2024, he has been responsible for formulating policies to promote the commercialization and growth of Japan’s space industry.

Tsubasa Nara

Tsubasa Nara

Mizuho Bank, Ltd.
Head, Innovation Companies Credit Office

PROFILE
He joined Mizuho Bank in 2000. After working in sales for mid-sized companies and large corporations, credit review for large corporations, loan planning and branch management, he took up his current position in 2023, heading the startup-focused credit department — the only department at a Japanese bank that also carries a client-facing relationship function. Centred on debt financing for startups, he supports their growth across a broad range of needs.

More speakers will be announced as they are confirmed.
Speakers and program are subject to change.

OUTLINE

Event Details

Name
G-SFIA 2026 (Global Space Financial Innovation Alliance)
Date & Time
Wednesday, 4 November 2026, 13:00-17:30
Rooftop Night 18:00-20:00
The full timetable will be announced in stages
Venue
Global Business Hub Tokyo (Otemachi, Tokyo)
The Rooftop Night is held at SKYLAB, Otemachi Building
Organizer
FINOLAB, Inc.
Admission
Please see the Peatix page
Early Bird tickets available
How to Register
Peatix registration page

ACCESS

Access

MAIN 13:00–17:30
Main Conference

Global Business Hub Tokyo

1-9-2 Otemachi, Chiyoda-ku, Tokyo 100-0004
Otemachi Financial City Grand Cube, 3F

Directly connected to Otemachi Station (Tokyo Metro)
About 8 min walk from JR Tokyo Station, Marunouchi North Exit

Open in Google Maps →

NIGHT 18:00–20:00
Rooftop Night

SKYLAB, Otemachi Building

1-6-1 Otemachi, Chiyoda-ku, Tokyo 100-0004
Rooftop, Otemachi Building

Directly connected to Otemachi Station (Tokyo Metro)
About 5 min walk from the main venue

Open in Google Maps →

SIDE EVENT

Side Events

SIDE EVENT 01

The future of space business, read from the SpaceX IPO

Wednesday, 21 October 2026, 18:30 – 20:30

Register on Peatix→

Overview & Speakers

Taking the SpaceX IPO as the starting point, this session brings together the side that runs space funds as an institutional investor, the space ventures actually raising the money, and the vehicles now opening to individuals opportunities that were once open only to institutions. From those who put capital in to those who receive it, we look at the full circulation of money through the space business.

  • Keiko Sydenham
    LUCA Japan, Representative Director & CEO
  • Kazuo Yonekura
    MJOLNIR SPACEWORKS, Representative Director & CEO
  • [Moderator] Misuzu Onuki
    SPARX Asset Management, Executive Vice President, Space Investment Team, Next Generation Growth Investment Department
SIDE EVENT 02

Space for Green Finance
Verifying Value Across Sectors

Thursday, 5 November 2026, 13:00-15:30

Register on Peatix→

Overview & Speakers

Co-organized by ESPI (the European Space Policy Institute) and FINOLAB.

In this seminar, companies that turn satellite data into business each answer, for their own sector: what decision does the data unlock, and what financial instrument or investment case does it enable? Green finance and sectoral decision-making are treated as a single continuum, not as two separate themes.

  • [Speaker] Naoko Sugita
    Program Manager, Earth Observation Program Strategy Office and Earth Observation Research Center, Japan Aerospace Exploration Agency (JAXA)
  • Hiroya Ishitsubo
    COO, Sagri
  • Bryan Atwood
    CEO, DAI Labs
  • Keitaro Asaba
    International Business Development, Tenchijin
  • Naruo Kanemoto
    CEO, Space Shift
  • [Moderator] Jara Villanueva
    ESPI Centre for Sustainability and Resilience

JOIN US

Register (Peatix)

Join us for a day where space and finance meet.
Registration is handled through the Peatix page.

Go to the Peatix page→

Wednesday, 4 November 2026, 13:00-17:30 / Global Business Hub Tokyo

ORGANIZER & SUPPORTERS

Organizer & Supporters

ORGANIZER
COOPERATING ORGANIZATION


PLATINUM

GOLD
BRONZE

PARTNERS

ARCHIVES

Past “Space × Finance” sessions

A seminar series FINOLAB has run since 2021.
G-SFIA builds on all of it. Click a thumbnail to watch the archived video.
[Summary] Expansion of Startup Fundraising – Deregulation and Emerging Trends | FinTech Topics #132

(Original Video in Japanese was published on the FINOLAB CHANNEL on Sep. 15, 2026 by Makoto Shibata) https://youtu.be/FgaaJaqEy1g

Japan has been introducing a series of regulatory reforms and new financial mechanisms to expand funding opportunities for startups. The starting point was the government’s Five-Year Startup Development Plan, adopted in November 2022. The strategy aims to fundamentally strengthen Japan’s startup ecosystem through three major pillars: developing entrepreneurial talent and networks, substantially increasing the supply of capital, and promoting open innovation between startups and established corporations. One of its headline objectives is to increase annual investment in startups to around ¥10 trillion within five years.

Since then, reforms have addressed different stages of startup growth and both sides of the investment relationship. Four particularly important areas are stock options, angel investment taxation, equity crowdfunding, and secondary markets for unlisted shares.

Stock options are important for startups because they allow companies with limited cash resources to attract and retain talented employees by sharing the potential upside of future growth. Japan has gradually made its stock-option regime more flexible. For qualifying stock options, taxation can be deferred from the time of exercise until the shares are sold. The exercise period was extended from ten to fifteen years in the FY2023 tax reform. The FY2024 reform further expanded the framework by introducing a system under which issuing companies can manage shares themselves and increasing the maximum annual exercise amount from ¥12 million to as much as ¥36 million. Legal reforms have also introduced a stock-option pool mechanism, giving startups greater flexibility in designing employee incentives.

The angel tax incentive has also been expanded to encourage investment at the pre-seed and seed stages. The system provides tax benefits to individual investors funding startups. Reforms introduced a Japanese version of the U.S. Qualified Small Business Stock concept, allowing preferential treatment when capital gains are reinvested in early-stage startups or used to establish a new business. Subsequent changes broadened eligible investments and extended the period during which capital gains can be reinvested. In FY2024, investments using the angel tax incentive reached approximately ¥18.5 billion, demonstrating the growing role of individual investors in startup financing.

A third area is equity crowdfunding. Japan introduced the framework in 2015, but initially imposed relatively strict limits: an individual could invest only ¥500,000 per company, while fundraising was effectively capped at ¥100 million. The rules have subsequently been relaxed. In 2022, the calculation method was changed so that companies could raise up to ¥100 million through crowdfunding alone. In 2025, the fundraising ceiling was raised to ¥500 million, while the individual investment limit was relaxed to 5% of the investor’s net assets, subject to a maximum of ¥2 million. At the same time, larger offerings remain subject to disclosure and auditing requirements, balancing easier access to capital with investor protection.

Perhaps the most significant structural development is the effort to establish a functioning secondary market for unlisted shares. Historically, Japan’s startup ecosystem has suffered from limited liquidity in private shares. Venture capital funds typically have a life of around ten years and eventually need to exit investments. Without an active secondary market, this has often meant relying on an IPO or M&A transaction. The lack of alternative liquidity has contributed to the problem of “small IPOs,” in which companies may go public before reaching sufficient scale simply to provide an exit opportunity for existing shareholders.

This contrasts with markets such as the United States, where platforms including Nasdaq Private Market, Forge Global, and EquityZen facilitate transactions in private-company shares. The United Kingdom also has markets and investment schemes designed to channel capital toward growing companies. Japan has created mechanisms such as the Japan Securities Dealers Association’s shareholder community framework and TOKYO PRO Market, but these have not generated comparable liquidity.

Regulatory reform is now attempting to change this situation. Traditionally, intermediating stock transactions required registration as a Type I Financial Instruments Business Operator, involving substantial capital and regulatory requirements that created high barriers to entry. An amendment to the Financial Instruments and Exchange Act enacted in 2024 introduced a special framework for intermediating unlisted securities. Requirements for individuals to qualify as professional investors have also been reviewed and clarified. These changes are intended to encourage new intermediaries and improve liquidity in private shares.

A more active secondary market could benefit several participants. Startups could avoid premature IPOs and pursue more flexible capital strategies. Venture capital funds and other existing shareholders could obtain liquidity without forcing portfolio companies to list. Investors would gain access to a broader range of private investment opportunities, while improved secondary-market liquidity could also encourage investment in primary fundraising rounds. For financial institutions, private-market intermediation could develop into a new business area as demand for private equity and alternative investments grows.

Several recent examples illustrate how the market is evolving. eCrowd combines equity crowdfunding with the angel tax incentive and has expanded into investment opportunities for middle- and later-stage companies through “eCrowd NEXT.” Smartround Securities, a subsidiary of Smartround, completed registration in August 2026 for the special unlisted-securities intermediation business, enabling it to develop secondary transactions in private shares. Meanwhile, LUCA Japan has created funds providing Japanese investors with exposure to selected late-stage U.S. private companies.

Another notable development is the combination of private equity with digital securities. In September 2025, SBI Securities, Shinsei Trust & Banking, Tokio Marine Asset Management, and BOOSTRY jointly developed Japan’s first private-equity fund investment product for individual investors using security-token technology. The product aims to broaden access to private-company investments that had traditionally been concentrated among institutional investors.

Overall, Japan’s startup-financing reforms represent more than a collection of deregulation measures. The broader policy direction is shifting from simply “increasing the number of public companies” to “increasing the number of growth companies.” The objective is not to create new markets or financial schemes for their own sake, but to build an ecosystem in which capital can circulate according to the different stages of startup growth. These reforms do not necessarily make fundraising easier, but they significantly expand the options available to entrepreneurs when designing their capital strategies—and, at the same time, broaden the range of opportunities available to investors.

[Summary]Four Conditions and Four Trends for Winning in Cross-Border Remittances, According to an Industry Veteran, CEO of Remitly

(Original article in Japanese by Makoto Shibata was published for FinTech Journal on Aug. 12, 2026) https://www.sbbit.jp/article/fj/186371

The cross-border remittance market has grown to roughly $2 trillion. While traditional banks still process the vast majority of international funds due to entrenched trust, digital fintechs are disrupting the sector. In an interview, Sebastian Gunningham—new CEO of Remitly and former executive at Oracle, Amazon, Apple, and WeWork—shared his core evaluation criteria for fintech companies, structural industry trends, and Remitly’s expansion strategy in Japan.

1. Four Conditions for Evaluating a Winning Company

Before joining Remitly in early 2026, Gunningham evaluated the firm using four strict business criteria:

  • Product Customer Love: Strong user experience and high app store ratings.
  • Market Size: A massive, expanding addressable market (~$2 trillion in personal remittances alone).
  • Moats/High Entry Barriers: A proprietary compliance framework, KYC/AML engine, and global licenses built over 10+ years that cannot be easily replicated.
  • Strong Unit Economics: Margin improvement as operating scale expands.

2. Remitly’s Network and Growth Engines

Remitly currently operates across 170+ countries with over 5,000 corridors (aiming to add 1,000 more in 2026) and serves 10 million active users. Beyond individual-to-individual family remittances, Remitly is pursuing three major growth drivers:

  • SMBs & Freelancers: Micro-businesses, sole proprietors, restaurant owners paying overseas staff, and digital content creators who find traditional bank transfers too complex and expensive.
  • High-Value Remittances: High-earning immigrants (e.g., tech workers sending over $10,000 for overseas real estate, investments, or personal savings).
  • Network-as-a-Service (NaaS): Partnering with traditional banks to process their cross-border payments on corridors banks cannot efficiently cover.

Additionally, Remitly is rolling out adjacent financial services (checking features, cards, and micro-loans earmarked strictly for remittance payments) to support underserved immigrant communities.

3. Four Megatrends Reshaping Global Finance

Gunningham identified four major macro shifts impacting fintech:

  • Rise of Digital Banks: Neobanks providing services at 1/10th the cost of legacy incumbents.
  • AI Accelerating Product Delivery: Rapid development speed where small teams could soon build bank prototypes over a weekend. While technical barriers are falling, regulatory barriers (KYC/AML) remain firm.
  • Regulatory Divergence: While the US shifts toward deregulation and active bank licensing, much of the rest of the world (including Japan) is tightening compliance rules.
  • Crypto and Stablecoins: High talent and capital inflow into blockchain rails.

4. Reality Check on Stablecoins

Despite the hype surrounding blockchain-based payments, Gunningham highlights three practical friction points:

  • Cost Efficiency: Remitly’s existing infrastructure is cheaper than blockchain transactions on 90% of its 5,000 corridors.
  • On-Ramp/Off-Ramp & Compliance: Beneficiaries ultimately require conversion into local fiat currencies (JPY, PHP, MXN), meaning compliance and local banking integrations remain unavoidable regardless of the underlying ledger.
  • Government & Currency Sovereignty: Many governments oppose the dollarization of their domestic economies through private USD-backed stablecoins. Furthermore, compelling real-world use cases for “programmable money” are still lacking.

5. Japan Strategy & Market Entry

Having secured a Type II Fund Transfer Service Provider license in Japan, Remitly is targeting Japan’s growing 4 million foreign resident population (primarily from Vietnam, China, the Philippines, and South Korea) alongside Japanese digital creators.

  • Growth Driver: Word-of-mouth recommendations within immigrant communities remain the single strongest customer acquisition tool, outperforming traditional advertising.
  • Key Success Drivers: Leveraging strict global compliance standards, lower fees, speed, and seamless digital adoption as Japan shifts away from a cash-heavy economy.

Conclusion

The competition in cross-border payments has evolved beyond a simple race on transfer speeds or low fees. The ultimate winners will be determined by who controls the underlying global network, regulatory compliance stack, and institutional banking partnerships.

[Summary]  Legal Regulations Surrounding DeFi – Directions Indicated by the FATF Report | FinTech Topics #131

(Original Video in Japanese was published on the FINOLAB CHANNEL on Aug. 11, 2026 by Makoto Shibata) https://youtu.be/sHzpXM4sHQw

Decentralized Finance, or DeFi, refers to financial services provided through automated programs, primarily smart contracts, on blockchain networks without relying on traditional centralized intermediaries such as banks, securities companies, or crypto-asset exchanges. Compared with conventional centralized finance, or CeFi, DeFi allows users to manage assets directly through their own wallets, interact peer-to-peer or with liquidity pools, and access financial services around the clock, often without conventional account-opening procedures or identity verification.

The underlying technology is blockchain, a distributed database in which transaction data is stored in interconnected blocks. Each block contains information linked cryptographically to the previous block, making unauthorized alteration detectable and allowing participants to verify the integrity of transaction records. This architecture provides the technological foundation for decentralized financial transactions.

DeFi has four important characteristics. First, smart contracts automatically execute transactions when predefined conditions are satisfied, reducing the need for manual intervention by third parties. Second, many DeFi services are permissionless, meaning that users can access them regardless of nationality, credit history, or whether they have a conventional bank account. Third, composability allows open-source DeFi protocols to be combined like building blocks to create new financial products and services. Fourth, DeFi is generally non-custodial, allowing users to retain control of their assets through their own crypto wallets rather than depositing them with a centralized institution.

These characteristics have enabled a wide range of financial services. Decentralized exchanges (DEXs) such as Uniswap allow users to exchange crypto assets directly with other users or liquidity pools. Lending protocols such as Aave enable users to earn interest by supplying assets or to borrow against crypto collateral. Other applications include stablecoins and synthetic assets, as well as yield farming, in which users provide liquidity to protocols in return for transaction fees or reward tokens.

However, the same characteristics that make DeFi innovative also create significant risks. With no centralized administrator, users may have limited protection when funds are mistakenly transferred, fraud occurs, or a protocol fails. Vulnerabilities in smart contracts can be exploited by hackers, resulting in large-scale losses. Moreover, the ability to transact without conventional identity verification and the pseudonymous nature of blockchain transactions can make DeFi attractive for money laundering, terrorist financing, and other forms of financial crime.

Against this background, the Financial Action Task Force (FATF) published a report on the regulatory challenges posed by DeFi in July 2026. The report reflects the rapid expansion of the DeFi ecosystem, including growing participation by institutional investors and virtual asset service providers (VASPs), while highlighting increasing risks related to money laundering, terrorist financing, and proliferation financing. Its objective is to clarify how FATF standards, particularly Recommendation 15, should apply to DeFi arrangements. A key principle is technological neutrality: regulation should focus not on a particular blockchain or smart contract itself, but on the individuals or legal entities that exercise control or sufficient influence over it.

The FATF framework therefore distinguishes among three types of DeFi arrangements according to their governance and control structures. The first is centralized DeFi, where identifiable developers, administrators, governance-token holders, or other parties exercise control. These arrangements are subject to FATF standards and may require licensing or registration. The second category consists of arrangements that are effectively centralized but whose controllers are difficult to identify because of pseudonymity or other factors. These are also considered within the scope of FATF standards, although enforcement can be difficult. The third category is truly decentralized DeFi, where no person exercises control or sufficient influence. Because technology itself cannot be regulated as a legal entity, such arrangements fall outside direct application of the standards, requiring alternative risk-mitigation measures.

This distinction is particularly important because calling a service “decentralized” does not necessarily mean that it is decentralized in practice. FATF therefore identifies both on-chain and off-chain indicators for determining who actually exercises control. On-chain indicators include possession of upgrade keys or backdoors, authority to change fees, interest rates or collateral ratios, control over price oracles, receipt of protocol revenues, and concentration of governance tokens or voting power. Off-chain indicators include control of websites and applications, authority over development roadmaps and infrastructure, management of trademarks and official communications, and employment or financing of developers by a company or foundation.

The need for such scrutiny is reinforced by the financial crimes associated with DeFi. These include fraud and Ponzi-type schemes, sophisticated laundering networks using combinations of cross-chain bridges, DEXs and mixers, hacking linked to proliferation financing, and governance attacks, where mechanisms such as flash loans may be used to temporarily acquire significant voting power and manipulate protocol decisions.

For national authorities, FATF recommends a risk-based approach. Countries should assess their exposure to DeFi risks, impose licensing or registration requirements where identifiable controllers exist, and consider embedding AML/CFT measures at the smart-contract level. Where controllers cannot be identified, authorities may need to rely more heavily on points of contact with the conventional financial system, including VASPs and stablecoin issuers, to conduct customer due diligence or freeze assets. FATF also emphasizes blockchain analytics, public-private partnerships, international cooperation, and mechanisms for rapidly tracing, freezing, and recovering illicit assets.

The report also places responsibilities on businesses. DeFi arrangements with identifiable controllers should comply with FATF Recommendation 15 and implement financial-crime controls. Governance structures, contact information, and the scope of control should be transparent. VASPs and financial institutions interacting with DeFi protocols are also expected to assess DeFi-related risks, conduct appropriate customer identification, and maintain real-time transaction monitoring.

Overall, the FATF report represents an important step toward establishing a more consistent international approach to DeFi regulation. Rather than treating all DeFi activities uniformly, it distinguishes between arrangements where identifiable parties exercise effective control and those that are genuinely decentralized. The emerging regulatory direction is therefore not to regulate decentralization itself, but to identify where actual control exists and apply proportionate, risk-based regulation accordingly. This approach seeks to preserve the innovative potential of DeFi while addressing its growing exposure to money laundering, financial crime, and other risks.

[Summary]: Tokenized Deposits – A New Choice for Digital Currency | FinTech Topics #130

(Original Video in Japanese was published on the FINOLAB CHANNEL on July 28, 2026 by Makoto Shibata) https://youtu.be/X1FhA6SiuiM

As financial services increasingly move “on-chain,” tokenized deposits are emerging as an important new form of digital money. They aim to combine the trust and stability of conventional bank deposits with the speed, programmability, and flexibility offered by blockchain and distributed ledger technology (DLT). Financial institutions in Japan and overseas are therefore exploring tokenized deposits as part of the next generation of payment and settlement infrastructure.

A tokenized deposit is essentially a digital representation of an existing commercial bank deposit issued on a blockchain or DLT network. It maintains a one-to-one relationship with conventional fiat-denominated deposits, such as yen or U.S. dollar deposits. Because commercial banks remain the issuers, tokenized deposits can operate within existing banking regulations and deposit frameworks while enabling funds to be transferred and settled digitally around the clock.

Tokenized deposits occupy a distinctive position among emerging forms of digital money. Stablecoins are generally issued by private companies and backed by reserve assets, while central bank digital currencies (CBDCs) are direct liabilities of central banks. Tokenized deposits, in contrast, remain liabilities of commercial banks and are legally treated as deposits. In Japan, this means that tokenized deposits fall primarily within the banking regulatory framework, whereas stablecoins are treated as payment instruments under the Payment Services Act. All three forms of digital money can potentially incorporate programmable functions, but their issuers, underlying assets, legal status, and risk structures differ significantly.

One of the most promising applications is Delivery versus Payment (DVP) for securities transactions. Conventional securities settlement involves separate processes for transferring securities and funds, creating time lags and counterparty risk. Although settlement cycles have been shortened internationally—for example, the U.S. securities market moved from T+2 to T+1 in May 2024—the basic challenge remains. By linking tokenized securities and tokenized deposits through smart contracts, the transfer of an asset and its payment could occur simultaneously, enabling atomic settlement. This could eventually facilitate T+0 settlement, reduce counterparty and settlement risks, lower collateral requirements, improve capital efficiency, and enhance market liquidity.

Another major benefit is 24/7 real-time settlement. Conventional interbank payments are still affected by banking hours and business days, while cross-border transactions often involve multiple correspondent banks and may take several business days. Tokenized deposits can be transferred continuously on blockchain networks, potentially enabling immediate settlement at night, on weekends, and on holidays. Such capabilities are becoming increasingly relevant as securities markets themselves consider longer trading hours and financial markets move toward continuous operation.

Tokenized deposits also introduce programmability through smart contracts. In conventional banking, contractual information and payment processing are usually handled through separate systems, requiring manual procedures such as invoice processing, credit checks, payment instructions, and approvals. With tokenized deposits, payment can be automatically triggered when predetermined contractual conditions are satisfied. For example, a payment could be executed immediately when a logistics system confirms that goods have been delivered. In corporate transactions and supply-chain finance, this could improve transparency, reduce administrative workloads, accelerate receivables collection, and make cash-flow management more predictable.

Another advantage is their compatibility with the existing regulatory framework. Because tokenized deposits are issued by regulated banks, they can be designed around established KYC and AML requirements. This may make them easier to integrate into existing banking services than entirely new forms of digital money. At the same time, interoperability will become increasingly important as different banks issue their own tokens. Common protocols and cross-chain technologies will be needed to enable settlement between different tokenized deposits and other tokenized financial assets.

Tokenized deposits could also provide a bridge between traditional banking and Web3 and decentralized finance (DeFi). Stablecoins such as USDT and USDC currently play an important role in DeFi, but concerns have been raised regarding issuer reliability, reserve transparency, and KYC/AML arrangements. Bank-issued tokenized deposits could offer a more regulated form of digital money for permissioned DeFi, where access is restricted to verified participants. This could create new opportunities for institutional lending, collateral management, corporate finance, and B2B payments.

Several initiatives demonstrate how the concept is already moving toward practical implementation. JPM Coin, operated on J.P. Morgan’s Kinexys blockchain platform, is backed one-to-one by bank deposits and is used mainly for large-value corporate payments and liquidity transfers. The platform has processed trillions of dollars in transactions, and experiments are also connecting it with tokenized securities and public blockchain infrastructure.

At the international level, Project Agorá, led by the Bank for International Settlements (BIS) and the Institute of International Finance (IIF), is exploring a next-generation cross-border payment infrastructure based on tokenization. The project brings together seven central banks and more than 40 private financial institutions and examines how tokenized commercial bank deposits and central bank reserves could be integrated using DLT. Its objective is to address longstanding problems in cross-border payments, including slow processing, high costs, and limited transparency.

Japan is also seeing practical initiatives. Hokkoku Bank’s Tochika represents an example of a bank-backed digital currency designed for payments and transactions within Ishikawa Prefecture, with the broader objective of supporting the circulation of funds within the regional economy. Meanwhile, Japan Post Bank is developing a DCJPY-based tokenized deposit and aims to provide settlement services linked to NFTs and security tokens during fiscal 2026.

Overall, tokenized deposits could become an important bridge between the conventional banking system and the emerging on-chain financial economy. They preserve the trust associated with commercial bank deposits while introducing capabilities such as DVP, real-time settlement, smart contracts, and connectivity with digital assets. The key challenge, however, will be integrating this new infrastructure with existing deposit and core banking systems. Ultimately, the pace of adoption may depend not only on blockchain technology itself, but also on how quickly and flexibly banks can transform their existing operational infrastructure.

[Summary]Why ZENTOSHIN’s 20-Year Fraud Led to a ¥125.9B Collapse: The Payment Infrastructure’s Biggest Blindspot”

(Original article in Japanese by Makoto Shibata was published for FinTech Journal on July 26, 2026) https://www.sbbit.jp/article/fj/186081

In July 2026, major Japanese credit card payment processing agency ZENTOSHIN (全東信) collapsed with liabilities of approximately ¥125.9 billion—marking the largest bankruptcy in Japan in 2026. The downfall exposed structural blind spots in Japan’s cashless payment infrastructure, triggering supply-chain failures for small merchant businesses and financial losses for regional lenders.

1. Scope of the Crisis & Downfall

  • Impact on Merchants: Rooted in restaurant cooperatives, ZENTOSHIN attracted small merchants with lenient screening and rapid payout options (e.g., payouts twice a week). Its sudden bankruptcy froze millions of yen in daily merchant sales, leaving small restaurants unable to pay rent, suppliers, or staff, leading to severe liquidity crises.
  • Hits to Regional Financial Institutions: 63 financial institutions were exposed. Small regional lenders (regional banks, Shinkin banks, and credit cooperatives) face non-recoverable debt from ZENTOSHIN, including Kinki Sangyo Credit Cooperative (¥22 billion), Tokyo Star Bank (¥8 billion), and Towa Bank (¥8 billion).
  • 20 Years of Accounting Fraud: ZENTOSHIN masked insolvency by overstating cash balances by ¥17 billion, creating ¥15.4 billion in fictitious receivables, overvaluing goodwill by ¥8.8 billion, and concealing ¥21.7 billion in unpaid merchant settlements. While reporting positive net assets of ¥2.5 billion, its actual financial state was a massive negative net worth of ¥60.5 billion.

2. Five Reasons the Fraud Went Unnoticed for 20 Years

  • Complex Flow of Funds: The constant, high-volume flow of funds between card companies, processing agencies, merchants, and banks made it difficult for auditors to distinguish between ZENTOSHIN’s corporate cash and temporary merchant funds.
  • Padding Bank Balances: ZENTOSHIN took advantage of borrowing across 63 different regional institutions, exploiting the lack of inter-bank balance verification to inflate deposit records undetected.
  • Chain of Blind Trust: Card companies, banks, and auditing entities operated under the assumption that other parties were conducting rigorous oversight, leaving a void in comprehensive oversight.
  • Lending Competition Among Regional Banks: Struggling with low interest rates, regional banks aggressively sought borrowers, ignoring thorough due diligence out of fear of losing business to competitors.
  • Private Company Regulatory Gap: As an unlisted entity, ZENTOSHIN was exempt from public disclosure and strict auditing under the Financial Instruments and Exchange Act, allowing management to hide fraud.

3. Structural Vulnerabilities in Payment Agencies

  • Absence of Segregated Fund Management Rules: Unlike securities or crypto exchanges, Japanese law (e.g., the Payment Services Act) did not strictly require payment processors to segregate held merchant funds from corporate operational cash. This allowed ZENTOSHIN to misappropriate merchant funds to cover operating losses.
  • Disguising Held Funds as Corporate Assets: Because payment processors naturally hold large daily cash flows, banks failed to spot artificially inflated bank balances as abnormal.
  • Shifting Risks to Vulnerable Small Businesses: When a processor fails, end merchants bear the brunt of the burden, forfeiting their own sales without insight into the processor’s financial health.

4. Key Regulatory Reforms & Global Comparisons

In response to the crisis, Japanese regulators (Financial Services Agency and METI) and the banking sector are considering stricter legal frameworks:

  • Mandatory Fund Segregation and Trust Safeguarding: Requiring processors to keep merchant funds in trust accounts to guarantee full, immediate returns to merchants upon processor bankruptcy.
  • Licensing & Mandatory External Audits: Transitioning payment processing from a open business model to a registration/licensing system with capital adequacy minimums and mandatory external CPA audits for large processors.
  • Regulation of Early Payout Schemes: Applying stricter credit management or reserve liquidity requirements for agencies offering accelerated payout options.
  • Alignment with Global Standards: Following models like the EU’s PSD2/EMD2, the UK’s FCA Safeguarding rules, and Singapore’s Payment Services Act, which mandate strict segregation, daily reconciliations, and independent trust accounts for payment institutions.
  • Joint Accountability for Card Networks & Acquirers: Holding primary acquirers and major card brands (Visa, Mastercard, JCB) jointly responsible for monitoring payment agency compliance.

Conclusion

The collapse of ZENTOSHIN highlights a crucial mismatch: payment processors have become critical social infrastructure, yet legally they were treated as basic IT service providers. Moving forward, regulatory updates will reclassify payment processing as a heavily regulated financial service to protect public assets and maintain faith in the cashless economy.

[Summary] Why Frontier AI Companies Choose Stripe & 4 Lessons for Japanese Enterprises

(Original article in Japanese by Makoto Shibata was published for FinTech Journal on June 26, 2026) https://www.sbbit.jp/article/fj/185683
 
Founded in 2010 by Patrick and John Collison, Stripe transformed online payments by providing developer-friendly API code, removing complex banking hurdles. Today, Stripe has evolved from a simple payment provider into a global “Financial OS” powering over 5 million businesses, including 90% of Dow Jones and 80% of Nasdaq 100 companies. By 2025, its Total Payment Value (TPV) reached $1.9 trillion (approx. 1.6% of global GDP), and its valuation reached $159 billion following a 2026 tender offer.
 
1. Key Factors Driving Stripe’s Success
Developer-First Philosophy: Stripe prioritized developer experience (DX) through easy API integration, robust documentation, sandbox environments, and actionable error codes, making it the de facto standard for tech startups.
 
Expansion into a Financial OS: Beyond payments, Stripe launched products like Billing (subscriptions), Radar (fraud protection), Atlas (incorporation), Connect (marketplaces), and Issuing (card creation).
 
The Choice of Frontier AI Firms: AI leaders—such as OpenAI, Anthropic, Mistral AI, and Perplexity—rely on Stripe for flexible monetization models (usage-based billing, multi-currency support, global subscriptions). Stripe is also co-developing the Machine Payments Protocol (MPP) with Tempo to support autonomous AI agent transactions.
 
Next-Gen Settlement via Stablecoins: Through strategic acquisitions like Bridge and Privy, Stripe is integrating USDC stablecoins to build a borderless, 24/7 real-time settlement network that complements or competes with Visa and SWIFT.
 
2. Competitive Advantage & Risks
Competitive Positioning: Stripe outperforms rivals (Adyen, PayPal, Square) in developer experience and rapid product expansion, dominating the market segment between early-stage startups and mid-to-large global enterprises.
 
Key Risks & Challenges:
Regulation & Compliance: Increasing scrutiny from global regulators (PSD2/PSD3, FTC) and crypto-related compliance costs.
Fraud & Chargebacks: Constant evolving threats despite AI-driven mitigation via Stripe Radar.
Dependency on Card Networks: Potential margin pressure from Visa/Mastercard interchange fee hikes.
Private Liquidity Risks: High valuation ($159B) creates pressure regarding eventual IPO plans and talent retention.
Tech Giants: Competition from Apple Pay, Google Pay, and Amazon Pay.
 
3. Four Key Lessons for Japanese Businesses
 
Adopt an “API-First” Strategy: Japanese payment gateways must focus heavily on developer experience and simple integration to capture growing startups.
Accelerate “Software-Defined Finance” (BaaS / Embedded Finance): Japanese financial institutions need to lower integration costs and modernize legacy core banking systems to embrace the API economy.
Design for “Global-First” Operations: Services (like Stripe Atlas) should be built cross-border from day one to serve international e-commerce and inbound tourism demand.
Prepare for the Convergence of AI and Stablecoins: Following Japan’s revised Payment Services Act and local stablecoin initiatives (e.g., JPYC), Japanese institutions must proactively balance regulatory compliance with building next-generation infrastructure.
 

[Summary]AI Threats and the Future of Financial System Resilience

Original article in Japanese by Makoto Shibata was published for FinTech Journal on May. 26, 2026) https://www.sbbit.jp/article/fj/185412

The emergence of frontier artificial intelligence (AI) systems capable of identifying and exploiting software vulnerabilities has triggered significant concern within the global financial sector. In particular, the pre-release AI model “Claude Mythos” demonstrated an unprecedented ability to discover vulnerabilities in major operating systems and web browsers, leading regulators and financial institutions in both the United States and Japan to reassess their cybersecurity strategies.

The fundamental impact of frontier AI is not simply that it accelerates vulnerability discovery. More importantly, it can automatically generate exploit code and conduct attacks at machine speed. This dramatically shortens the cyberattack cycle and increases the likelihood of large-scale zero-day attacks. As a result, traditional security approaches based on preventing intrusions and applying periodic patches are becoming insufficient.

The report argues that financial institutions must shift their focus from strengthening defenses to strengthening their ability to detect, respond to, and rapidly repair vulnerabilities. This represents a significant change in operational philosophy. Instead of assuming systems can be fully protected, organizations must assume vulnerabilities will inevitably be discovered and exploited.

Another important implication is the growing limitation of the long-standing objective of uninterrupted system operation. Financial institutions have traditionally pursued 24/7 availability, real-time processing, and non-stop services. However, in an AI-driven threat environment, the ability to safely suspend operations, isolate affected systems, and recover quickly may become more important than maintaining continuous availability at all costs.

The report also highlights risks associated with legacy systems and closed networks. Many Japanese financial institutions continue to rely on aging mainframe-based infrastructures built with legacy programming languages such as COBOL. While these systems have historically provided stability and reliability, frontier AI may be particularly effective at analyzing complex architectures, uncovering hidden vulnerabilities, and identifying attack paths. Consequently, system complexity and age may become liabilities rather than strengths.

Japan’s highly centralized financial infrastructure presents additional challenges. Critical platforms such as payment networks and shared banking systems create efficiency but also introduce concentration risk. A successful AI-enabled attack against these common infrastructures could disrupt large portions of the financial system simultaneously and generate systemic consequences extending beyond individual institutions.

The report further warns that regional banks and smaller financial institutions may face greater difficulties because of limited cybersecurity expertise, aging systems, dependence on vendors, and shared service platforms. Japan’s multi-layered outsourcing structure within financial IT may also delay vulnerability management and obscure accountability.

To address these challenges, several priorities are identified. Financial institutions should adopt integrated DevSecOps practices, strengthen identity and access management, conduct realistic cyber exercises, improve IT governance, and establish robust AI governance frameworks. Investment in human resources is equally important, particularly professionals who possess expertise across finance, AI, and cybersecurity.

Finally, the report emphasizes the importance of public-private cooperation, international information sharing, and supply-chain security. Since AI-driven cyber threats transcend organizational and national boundaries, effective responses will require collaboration among governments, financial institutions, technology providers, and AI developers.

In conclusion, the rise of frontier AI represents more than a cybersecurity challenge. It requires a fundamental transformation of financial system operations—from a culture focused on uninterrupted service to one centered on resilience, rapid recovery, and adaptive risk management in the AI era.

[Summary] Transformation of Cybercrime

(Original article in Japanese by Makoto Shibata was published for FinTech Journal on May. 11, 2026) https://www.sbbit.jp/article/fj/184958

The article examines how cybercrime is evolving based on the FBI’s latest Internet Crime Report and discusses the implications for Japan’s financial sector. It argues that cybercrime is no longer primarily a technology problem, but increasingly a challenge of financial system design and customer behavior.

FBI Internet Crime Report 2025: https://www.ic3.gov/AnnualReport/Reports/2025_IC3Report.pdf

According to the FBI’s 2025 report, more than one million cybercrime complaints were submitted in the United States, with total reported losses reaching approximately US$21 billion, a 26% increase from the previous year. Cryptocurrency-related crimes accounted for the largest share of losses, exceeding US$11 billion. The report also introduced a dedicated section on artificial intelligence (AI) for the first time, highlighting nearly US$900 million in damages linked to AI-enabled fraud. Criminals are increasingly using AI to generate phishing messages, impersonate executives, and steal credentials.

A notable trend is the shift from traditional “system intrusion” attacks to social engineering. Investment scams, business email compromise (BEC), technical support fraud, romance scams, and identity theft now account for the majority of financial losses. Rather than hacking financial institutions directly, criminals manipulate victims through social media, messaging platforms, and other communication channels, convincing them to initiate legitimate-looking transactions themselves. The article notes that approximately 85% of reported losses are linked to such social engineering schemes.

The author argues that Japan is already experiencing the same structural transformation. SNS-based investment fraud, romance scams, and other forms of deception have caused substantial losses, demonstrating that cybercrime increasingly targets human decision-making rather than technical vulnerabilities. As a result, financial institutions must expand their focus beyond cybersecurity to include monitoring customer behavior and transaction intent. The article introduces the concept of “Know Your Purpose,” suggesting that institutions should assess the legitimacy and context of transactions, not merely verify customer identity.

Another key issue is the growing complexity of money flows. Criminals often move funds across multiple layers, including bank transfers, money transfer operators, and cryptocurrency exchanges. The report warns that as Japan develops a regulatory framework for stablecoins and digital assets, similar risks may become embedded within the financial system. Effective countermeasures will therefore require cooperation across banking, payments, and cryptocurrency sectors rather than institution-by-institution responses.

The article also highlights the importance of combating fraudulent account creation and account trafficking. Stronger identity verification through technologies such as My Number card IC-chip authentication, combined with industry-wide sharing of suspicious account information, could significantly disrupt criminal networks. Likewise, in an era of instant payments, the ability to detect and freeze suspicious transactions in real time becomes as important as payment speed itself.

Finally, the article emphasizes the dual role of AI. While AI enables more sophisticated fraud, it can also be used to enhance behavioral analytics and anomaly detection. The discussion references concerns surrounding advanced AI models such as Anthropic’s Claude Mythos, which reportedly demonstrated the ability to identify and exploit software vulnerabilities, highlighting the growing cyber risks associated with rapid AI development.

The article concludes that Japan’s financial industry should prioritize three actions: implementing customer-behavior-based risk management, strengthening real-time data sharing across the industry, and building infrastructure capable of immediately delaying, suspending, or freezing suspicious transactions. The ultimate challenge is to create a financial system that balances convenience with security and positions financial institutions as critical social infrastructure for preventing fraud.

[Summary] QR Payments Across Asia: Standardization and Cross-Border Connectivity | FinTech Topics #129

(Original Video in Japanese was published on the FINOLAB CHANNEL on June. 23, 2026 by Makoto Shibata) https://youtu.be/vANj5aDSK5c

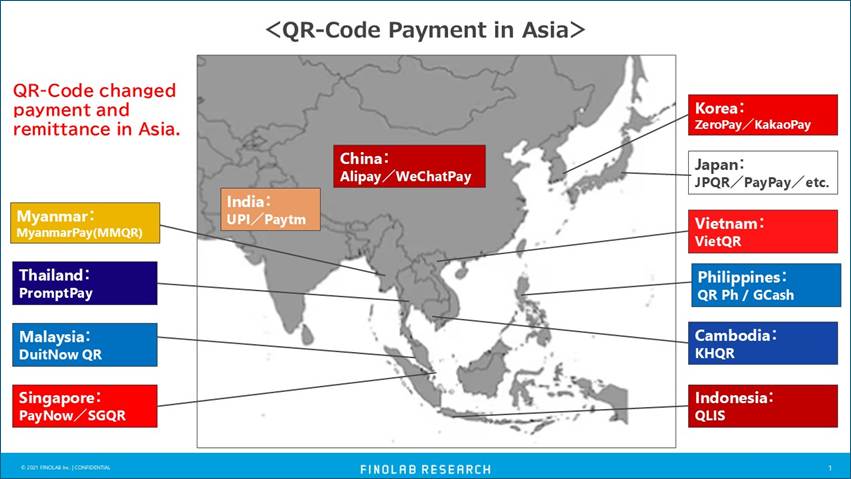
QR-code payments have become one of the most important innovations in Asia’s digital payment landscape. Although QR codes were originally invented in Japan, their large-scale adoption for consumer payments began in China and has since spread throughout Asia. Today, QR payments are transforming how people make purchases, transfer money, and conduct cross-border transactions.

China played a pioneering role through the rapid growth of Alipay and WeChat Pay. Supported by the widespread adoption of smartphones, these services evolved into “super apps” that integrate payments with messaging, e-commerce, transportation, and many other daily activities. Together they dominate China’s mobile payment market and have expanded their usability across many Asian countries.

Other Asian countries have followed different paths but share a common trend: government-led development of real-time payment infrastructure linked to QR-code technology.

India’s Unified Payments Interface (UPI), introduced in 2016, is one of the most successful examples. UPI enables instant transfers and payments through mobile applications, phone numbers, and QR codes. It has become the dominant payment infrastructure in India and is often cited as one of the world’s largest real-time payment systems.

Singapore introduced PayNow for instant payments and later launched SGQR, a unified QR standard that allows multiple payment providers to be accepted through a single QR code. Similarly, Thailand’s PromptPay, Indonesia’s QRIS, Malaysia’s DuitNow QR, the Philippines’ QR Ph, Vietnam’s VietQR, Cambodia’s KHQR, and Myanmar’s MMQR all represent national efforts to standardize QR payments and ensure interoperability among banks, e-wallets, and payment providers.

Japan presents a unique case. Despite being the birthplace of QR-code technology, the country initially experienced fragmentation, with many competing payment services such as PayPay and others. To address this issue, the Cashless Promotion Council introduced JPQR, a unified QR payment standard. More recently, Japan has begun connecting JPQR with overseas systems, including those of Cambodia and Indonesia, improving convenience for international visitors and businesses.

A major trend highlighted in the presentation is the shift from national standardization to international connectivity. Singapore has taken a leadership role by linking PayNow with Thailand’s PromptPay and subsequently connecting with payment systems in India, Malaysia, and Indonesia. Additional links with other ASEAN countries are under development. Meanwhile, Alipay has established partnerships with more than 50 payment providers across Asia, creating a broad network of interoperable QR payment services.

Another emerging development is the integration of stablecoins into QR payment infrastructures. Pilot projects are exploring how stablecoins can serve as the settlement layer behind QR transactions, enabling 24/7 cross-border payments with lower foreign-exchange and transaction costs. Examples include stablecoin payment trials in Japan and initiatives by regional platforms such as Grab.

In conclusion, QR payments have evolved from a simple payment method into a strategic digital infrastructure for Asia. Governments have promoted common standards and interoperability, while cross-border connections are gradually creating a seamless regional payment network. Looking ahead, the combination of QR payments, real-time settlement systems, and stablecoin technology may further accelerate financial integration across Asia.